Financial literacy in schools is becoming an important part of modern education because students need to understand how money works before making financial decisions as adults. Learning about saving, budgeting, spending, and responsible borrowing can help students develop practical skills that complement their academic knowledge.
The importance of financial education for students extends beyond understanding currency or calculating costs. It involves learning how to plan expenses, compare choices, set financial goals, recognise misleading offers, and make informed decisions. These abilities can support students as they become more independent.
By introducing financial literacy in schools, educators can help learners develop money management skills for students through classroom activities, practical examples, and age-appropriate financial exercises. Starting early gives students opportunities to practise responsible habits before facing more complex financial responsibilities.
Table of Contents
- What Is Financial Literacy in Schools?
- Why Financial Literacy Should Begin During School Years
- Seven Benefits of Financial Education for Students
- How Schools Can Teach Financial Literacy
- The Role of Parents in Financial Learning
- Conclusion
- Frequently Asked Questions
What Is Financial Literacy in Schools?
Financial literacy in schools means teaching students how to understand and manage money responsibly. It introduces concepts such as budgeting, saving, spending, financial planning, banking, and basic financial safety.
For example, students can learn how to divide a fixed allowance between spending and saving. They might compare the prices of different products, plan the budget for a class activity, or calculate how long it would take to save for a chosen goal.
These activities connect mathematical knowledge with everyday decisions. Financial literacy in schools also helps students understand that money is a limited resource and that different choices can have different consequences.
Financial education does not require students to make complicated investments. Its main purpose is to build a foundation of knowledge and practical decision-making skills that can develop as students grow older.
Why Financial Literacy in Schools Matters
Financial literacy in schools matters because young people gradually begin making independent decisions about purchases, savings, and digital transactions. Without basic financial knowledge, it can be difficult to compare options, plan expenses, or understand the consequences of financial choices.
Introducing financial concepts during the school years gives students time to ask questions, practise budgeting, and learn from everyday examples in a supportive environment.
The importance of financial education for students is particularly clear when they begin managing pocket money, purchasing school supplies, or saving for personal goals. These experiences provide opportunities to practise financial responsibility before facing more complex decisions in adulthood.
7 Benefits of Financial Literacy in Schools
1. Develops Budgeting Skills
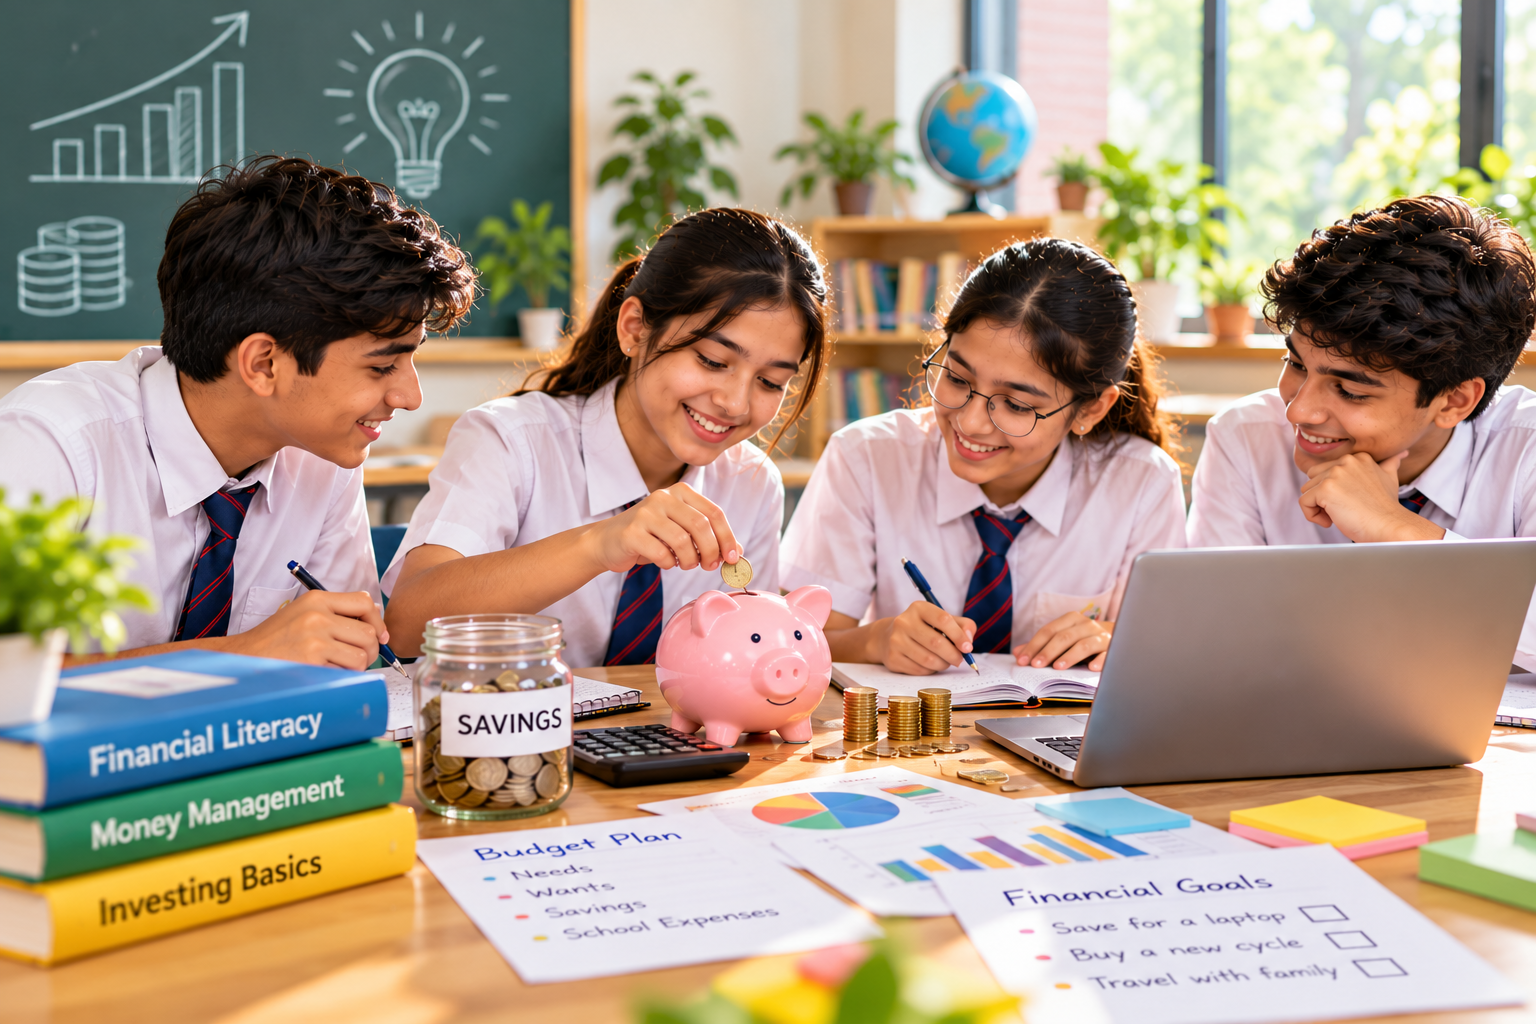
One of the main benefits of financial literacy in schools is learning how to prepare a budget. A budget helps students understand how much money is available and how it can be divided between different needs and goals.
For example, a student receiving a fixed weekly allowance could allocate part of it to school expenses, part to savings, and the remainder to optional purchases.
This activity teaches students to distinguish between essential expenses and wants. It also demonstrates that spending more in one area may leave less money available for another.
By practising simple budgets, students develop money management skills for students that can be useful throughout their lives.
2. Encourages Saving Habits
Saving is an important concept in financial education. Students can learn to set realistic goals, decide how much money to save regularly, and monitor their progress.
For instance, a student who wants to purchase a book or another suitable item can estimate its cost and calculate how much needs to be saved each week.
Financial literacy in schools helps students understand that saving often requires planning and patience. It also introduces the idea of keeping money aside for unexpected needs rather than spending everything immediately.
These habits can encourage thoughtful decision-making and help students recognise the value of planning ahead.
3. Promotes Responsible Spending
Students regularly encounter choices about what to buy, how much to spend, and whether a purchase is necessary. Financial literacy in schools can help them evaluate these decisions more carefully.
Teachers can introduce activities in which students compare product prices, examine quality, calculate discounts, or choose between several items within a fixed budget.
Such exercises help students understand that the cheapest option is not always the most suitable and that advertisements do not necessarily provide all the information needed to make a decision.
Learning to compare options and consider priorities strengthens the importance of financial education for students and encourages responsible consumer behaviour.
4. Builds Decision-Making Skills
Financial decisions often involve choosing between competing priorities. Students may need to decide whether to spend money immediately, save for a larger goal, or wait until they have more information.
Financial literacy in schools can help learners consider the costs, benefits, and possible consequences of different choices.
For example, students might compare purchasing an item immediately with saving for a more suitable option later. They can discuss which choice fits their budget and personal goal.
These activities strengthen reasoning and help students understand that responsible money management involves more than calculating numbers.
5. Introduces Banking and Digital Financial Safety
Modern financial transactions increasingly involve bank accounts, payment cards, mobile applications, and online purchases. Students should understand basic financial safety before using these services independently.
Age-appropriate financial education can explain concepts such as account security, private identification information, suspicious messages, and the importance of verifying payment requests.
Financial literacy in schools can also help students recognise common warning signs of scams, including unrealistic promises, urgent requests for money, and links from unknown sources.
The aim is to build awareness and encourage young people to consult trusted adults when a financial request or transaction seems suspicious.
6. Prepares Students for Adult Responsibilities
As students grow older, they may need to understand bank accounts, education expenses, salaries, taxes, loans, and household budgets. Basic financial knowledge can make these concepts easier to understand.
Financial literacy in schools introduces foundational ideas gradually, allowing students to build their understanding before facing more complicated responsibilities.
Older students can learn how interest works, how borrowing creates repayment obligations, and why it is important to read financial terms carefully.
The importance of financial education for students lies in preparing them to ask informed questions and evaluate financial choices rather than making decisions without understanding the consequences.
7. Supports Long-Term Financial Planning
Financial planning involves setting goals and considering how current decisions may affect future needs. Students can begin practising this skill through simple, realistic activities.
They might do a savings plan, estimate the cost of a school project, or compare the expenses and two hypothetical choices.
Financial literacy in schools helps learners understand that long-term goals often require regular saving, careful planning, and adjustments when circumstances change.
These experiences can provide a foundation for managing future education expenses, personal savings, and other financial responsibilities.
How Schools Can Teach Financial Literacy
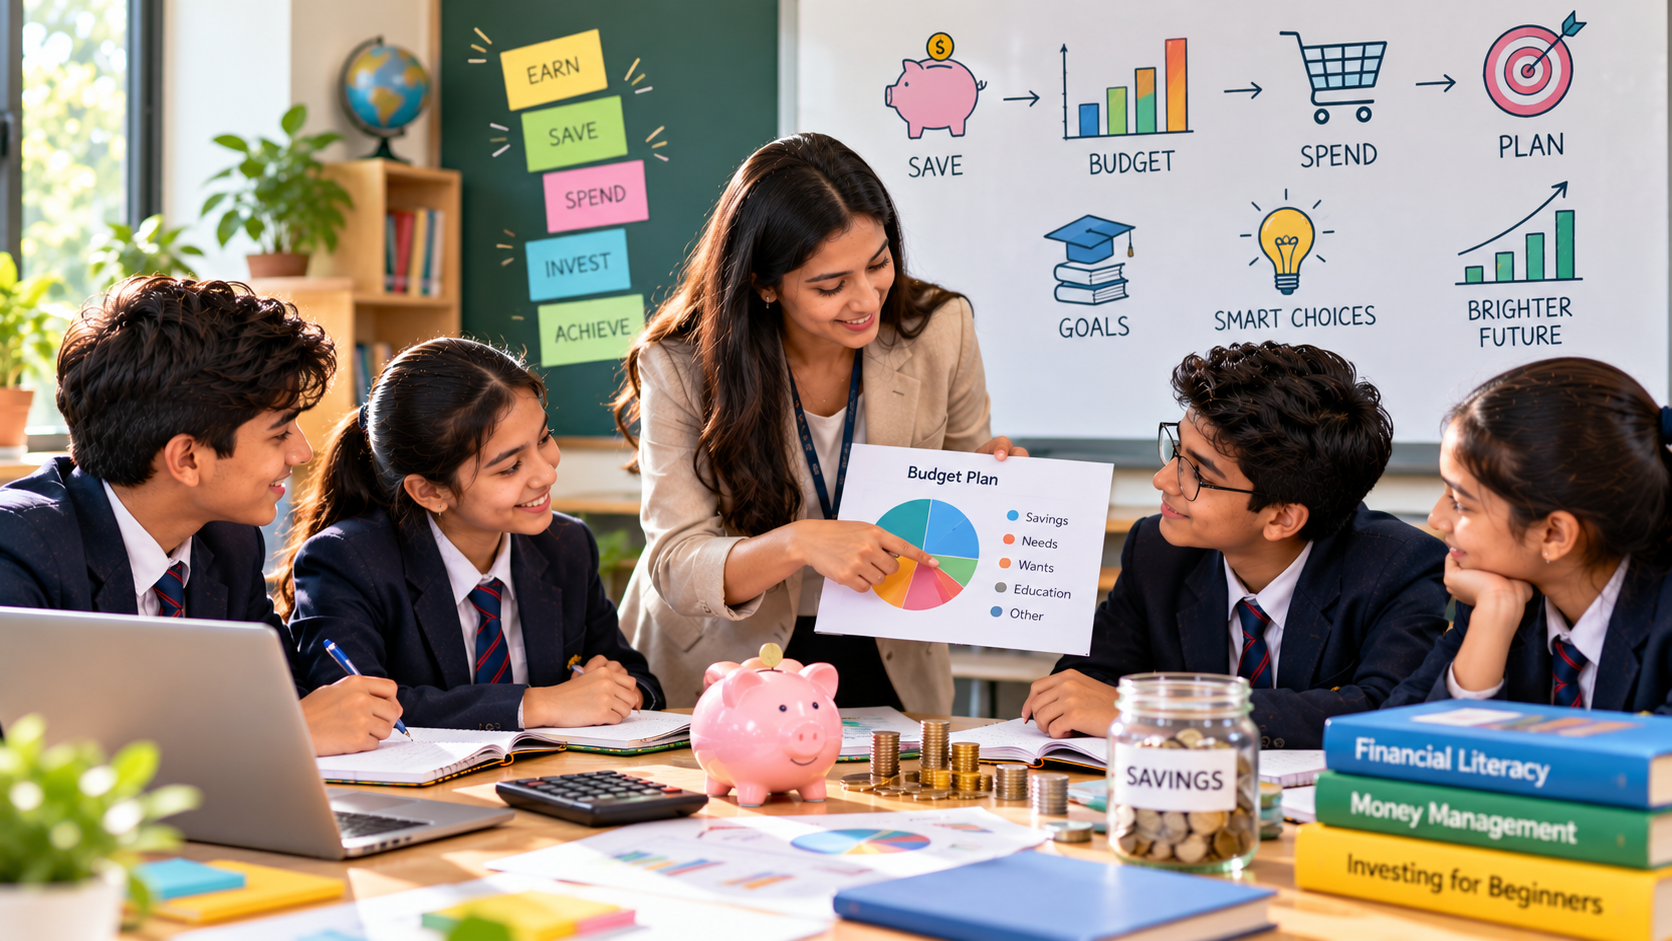
Schools can make financial literacy in schools more engaging by connecting financial concepts with practical activities and familiar situations.
Classroom Budgeting Activities
Teachers can give students a hypothetical allowance and ask them to divide it between needs, wants, savings, and planned expenses. Students can explain their choices and compare different budgets.
Practical Mathematics Exercises
Lessons can include calculating discounts, comparing prices, working out savings targets, and understanding simple interest. These exercises show how mathematical skills apply to everyday financial decisions.
Financial Decision-Making Projects
Students can work in groups to plan a school event within a fixed budget. They must estimate costs, compare suppliers, prioritise spending, and explain their final choices.
Age-Appropriate Banking Lessons
Older students can learn about bank accounts, payment methods, interest, borrowing, and digital financial safety. Teachers should use suitable examples and avoid encouraging students to enter financial agreements independently.
Games and Simulations
Budgeting games and simulated shopping activities allow students to explore financial choices in a controlled learning environment. Students can observe how spending decisions affect the money available for other priorities.
These methods help turn financial literacy in schools into a practical learning experience rather than a subject based only on definitions.
The Role of Parents in Financial Learning
Parents can reinforce financial literacy in schools by discussing everyday money decisions with their children. Simple activities at home can help students apply classroom concepts to familiar situations.
For example, parents might involve children in comparing grocery prices, planning a small purchase, or setting a savings goal. These activities provide opportunities to discuss needs, wants, budgets, and priorities.
Parents can also encourage children to ask questions about spending and saving rather than treating money as a topic that cannot be discussed.
The goal is not to place adult financial responsibilities on children. Instead, it is to help them develop age-appropriate awareness, practical skills, and responsible habits gradually.
Conclusion
Financial literacy in schools helps students develop the knowledge and habits needed to make informed decisions about money. Learning about budgeting, saving, spending, financial safety, and planning can connect classroom education with real-life situations.
By incorporating practical exercises, budgeting activities, financial games, and age-appropriate lessons, schools can make money management easier for students to understand and practise.
The importance of financial education for students extends beyond their school years. With guidance from teachers and parents, students can develop a strong foundation for managing money responsibly as they move towards greater independence.
Frequently Asked Questions
Q1. Why is financial literacy important in schools?
Ans: Financial literacy helps students understand budgeting, saving, responsible spending, financial safety, and planning. These skills can support better financial decisions as students become more independent.
Q2. At what age should students learn financial literacy?
Ans: Introduce basic concepts such as saving, comparing prices, and distinguishing needs from wants in primary school. More advanced topics, including banking, interest, and borrowing, can be introduced gradually as students mature.
Q3. What are money management skills for students?
Ans: Money management skills for students include preparing a budget, setting savings goals, comparing prices, prioritising expenses, and understanding the consequences of financial decisions.
Q4. How can teachers teach financial literacy?
Ans: Teachers can use budgeting exercises, practical mathematics, simulated shopping activities, group projects, and age-appropriate lessons about banking and digital financial safety.
Q5. How can parents support financial education?
Ans: Parents can involve children in everyday budgeting discussions, encourage savings goals, explain the difference between needs and wants, and model thoughtful spending decisions.